For years, bonus depreciation was a countdown clock — 100%, then 80%, 60%, 40%. The One Big Beautiful Bill Act stopped the clock for good: 100% first-year expensing is permanent for qualified property acquired and placed in service after January 19, 2025. That turns depreciation from a race against deadlines into a genuine planning tool. Here's how to use it well.
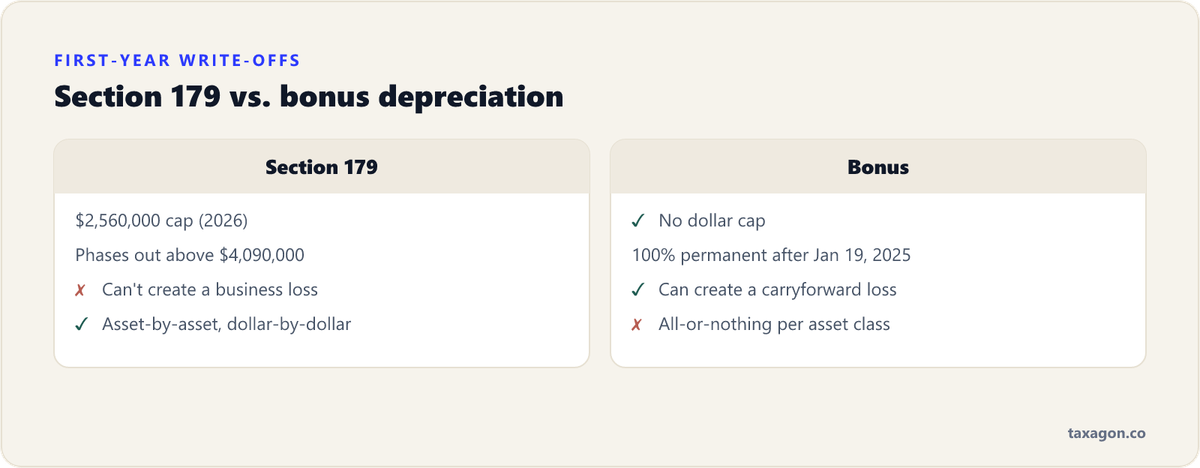
Both produce first-year write-offs; they behave differently at the edges. Section 179 for 2026 caps at $2,560,000 (phasing out above $4,090,000 of purchases), can't create a business loss, and can be taken asset-by-asset, dollar-by-dollar. Bonus depreciation has no dollar cap, CAN create a loss you carry forward, but is all-or-nothing per asset class per year. The usual sequencing: 179 first for precision, bonus for the rest.
A cost segregation study carves a purchased or renovated building into components — flooring, electrical, site work, fixtures — that qualify as 5-, 7-, or 15-year property, all eligible for 100% bonus. On a $1M+ commercial property, first-year deductions of 20–30% of the purchase price are common. With 100% bonus now permanent, cost seg went from nice-to-have to standard practice for anyone buying business real estate. (Rental owners: passive-loss rules decide how much you can use — plan before, not after.)
The biggest write-off year isn't always the smartest. Consider electing out (by asset class) when:
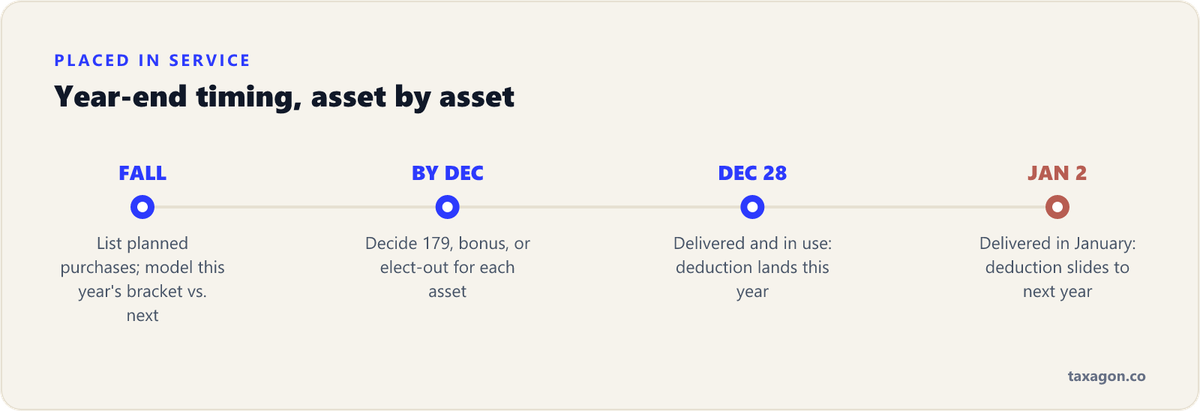
The deduction belongs to the year the asset is placed in service — in use, not ordered, not paid for. December 28 delivery: this year. January 2: next year. Plan backorders accordingly.
The right move every fall: list planned purchases, model this year's bracket versus next, and decide 179/bonus/elect-out per asset before December. That's a 30-minute exercise with your accountant that regularly moves five figures.
This guide is the hub — each of these covers one specific situation in detail:
Talk it through with a licensed US tax professional — we'll tell you honestly whether it applies to your situation.