Every spring we meet smart, well-paid people staring at five-figure surprise tax bills — and almost every time, equity compensation is the reason. Not because the rules are unfair, but because three different instruments are taxed three different ways and nobody explained any of them.
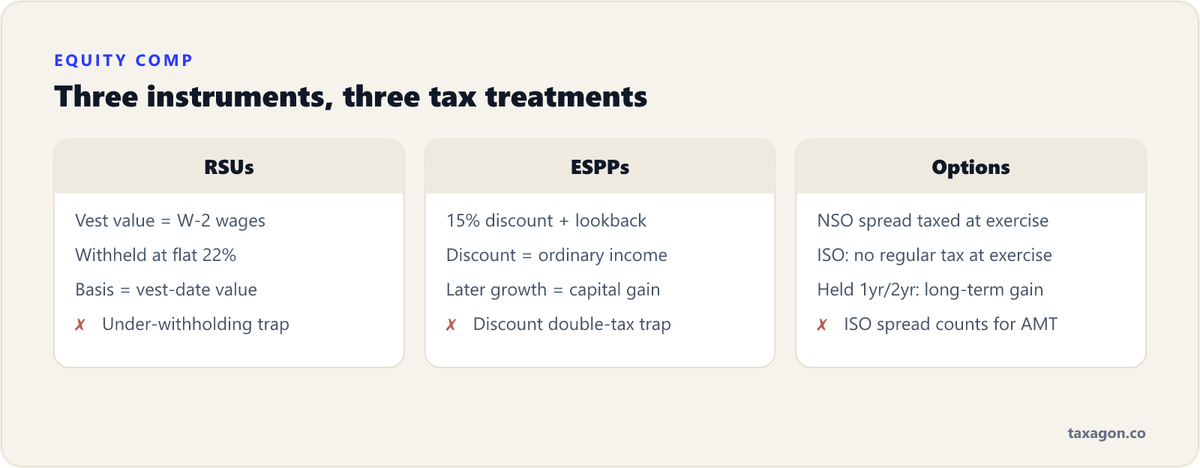

Restricted stock units are simple at heart: when shares vest, their market value is W-2 wage income — taxed like a cash bonus whether you sell or hold. The trap is withholding: most companies withhold on RSU vests at the flat supplemental rate of 22%. If your real marginal bracket is 32–37%, every vest silently under-withholds by 10–15 points. Vest $200,000 during the year and you can be $25,000 short in April — plus estimated-tax penalties on top.
A 15% purchase discount with a lookback provision is one of the best deals in personal finance — the discount can effectively exceed 15% when the stock rose during the offering period. The taxation splits in two: the discount element is ordinary W-2 income (timing depends on holding period), and price movement after purchase is capital gain.
The booby trap: the discount reported on your W-2 is part of your basis, but broker 1099-Bs often report only what you paid. Copy the broker number blindly and you pay tax on the discount twice. A qualifying disposition (held 2 years from grant, 1 year from purchase) improves the character of the income; a disqualifying one doesn't end the world — but the basis adjustment matters every single time.
Exercise = ordinary income on the spread between strike and market value, withheld like a bonus (with the same 22% under-withholding issue). Growth after exercise is capital gain.
The famous ones — and the dangerous ones. No regular tax at exercise, and if you hold 1 year past exercise and 2 past grant, the entire gain from strike price up is long-term capital gain. The danger is the alternative minimum tax: the exercise spread counts as AMT income the year you exercise, even though you received no cash. People who exercised heavily at a high valuation and watched the stock fall have owed six-figure AMT on gains that no longer existed.
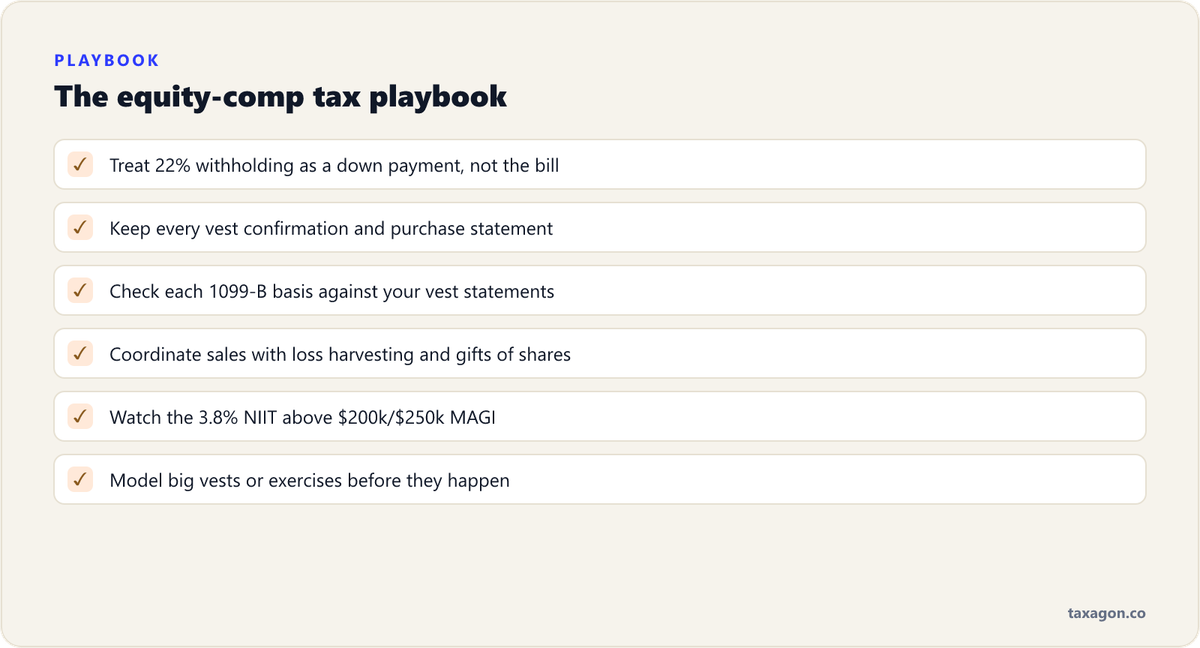
One planning session in the fall routinely saves equity-compensated employees more than any other hour of tax work all year. If a chunky vest is on your calendar, bring it to us before it happens.
This guide is the hub — each of these covers one specific situation in detail:
Talk it through with a licensed US tax professional — we'll tell you honestly whether it applies to your situation.


