For years, entity planning came with an asterisk: "...until the TCJA expires." The One Big Beautiful Bill Act deleted the asterisk. The 20% QBI deduction is permanent, the 21% corporate rate is permanent, and the qualified small business stock exclusion got bigger. Here's how the decision actually works now.
An LLC is a legal wrapper; S corp and C corp are tax elections. A single LLC can be taxed as a sole proprietorship, an S corp, or a C corp without ever changing its name. So the real question is never "LLC or S corp" — it's "how should my LLC be taxed?"
Profit passes to your 1040 and bears income tax plus 15.3% self-employment tax, softened by the QBI deduction. Zero payroll admin, maximum flexibility. It's the right answer while profits are modest — the S corp's savings have to outrun its costs before switching makes sense.
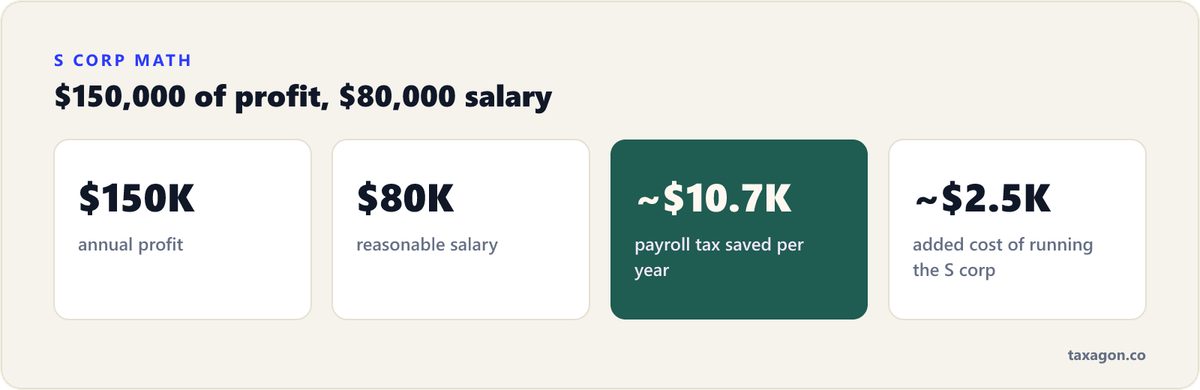
Pay yourself a reasonable salary; remaining profit skips self-employment tax. The savings are roughly 15.3% of the profit-above-salary — minus the new overhead: payroll service, a separate 1120-S filing (and its $255/owner/month late penalty), and possibly state franchise taxes. In practice the math starts working around $50,000–$60,000 of consistent annual profit, and gets compelling fast above that. Example: $150,000 profit, $80,000 reasonable salary — about $10,700 of annual payroll tax saved, against maybe $2,500 of added cost.
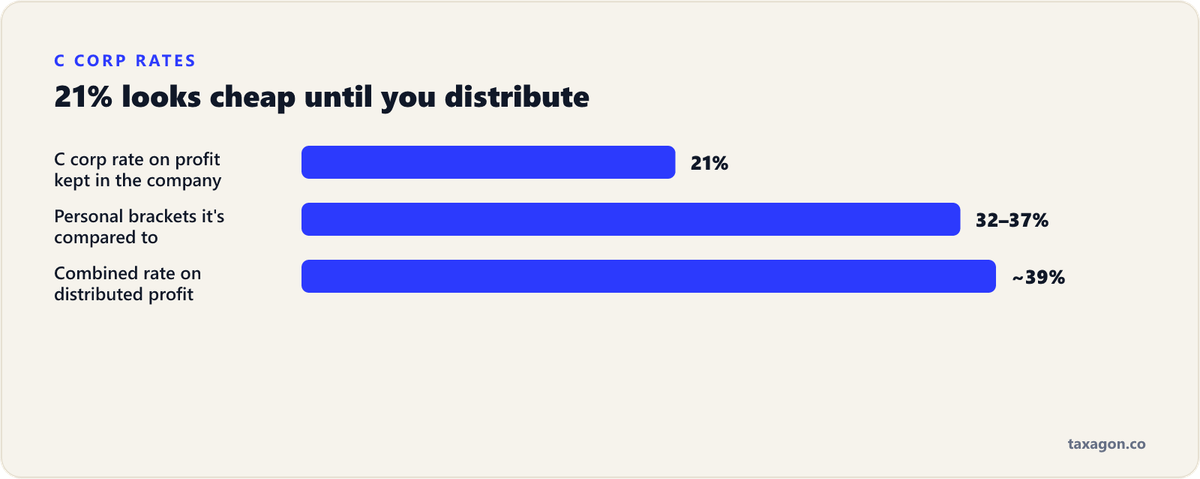
The 21% corporate rate looks tempting next to a 32–37% personal bracket, but dividends get taxed a second time on the way out — the combined rate on distributed profit lands near 39%. C corps make sense in specific patterns:
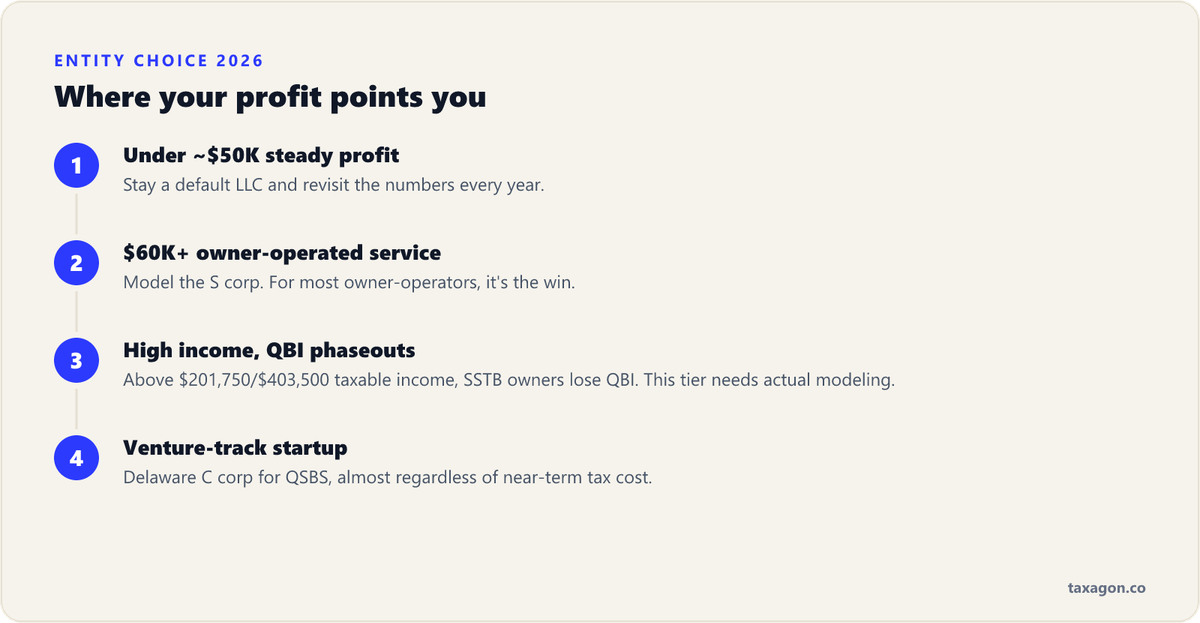
The expensive mistake isn't picking wrong on day one — it's never re-running the numbers as profit grows. The entity that was right at $40k is often wrong at $200k.
A one-hour entity review with your real numbers settles this for good — and if a switch makes sense, a clean January 1 effective date is exactly three months away.
This guide is the hub — each of these covers one specific situation in detail:
Talk it through with a licensed US tax professional — we'll tell you honestly whether it applies to your situation.