Twenty percent of your business profit, deducted before tax is calculated, without spending a dollar — that's the qualified business income deduction, and the 2025 tax law made it permanent. It also widened the phaseout ranges and added a small-business minimum. If you run any pass-through — sole proprietorship, LLC, S corp, partnership — this is likely your single largest deduction, and also the easiest to accidentally shrink.
QBI = your share of qualified net business profit (not W-2 wages you pay yourself, not capital gains, not interest). The deduction is generally 20% of QBI, limited to 20% of your taxable income minus net capital gains. It's a personal deduction taken on your 1040 — the business's books never see it — and you get it on top of the standard deduction.

Specified service trades or businesses — health, law, accounting, consulting, financial services, athletics, performing arts, and any business whose asset is the owner's reputation — get zero QBI deduction once income clears the top of the range. A consultant couple with $600k of taxable income loses a deduction a contractor couple with identical income keeps. If you're an SSTB owner near the thresholds, income management (retirement plans, timing, charitable bunching) is worth real money: every dollar kept below the range can preserve 20 cents of deduction.
Above the thresholds, non-SSTB owners keep the deduction only up to the greater of 50% of W-2 wages paid, or 25% of wages plus 2.5% of qualifying property. This creates a genuine paradox for S corp owners: a lower salary saves payroll tax but can shrink the wage limit and cost QBI at high incomes. The optimal salary is a joint calculation — anyone who set theirs before the QBI era should re-run it.
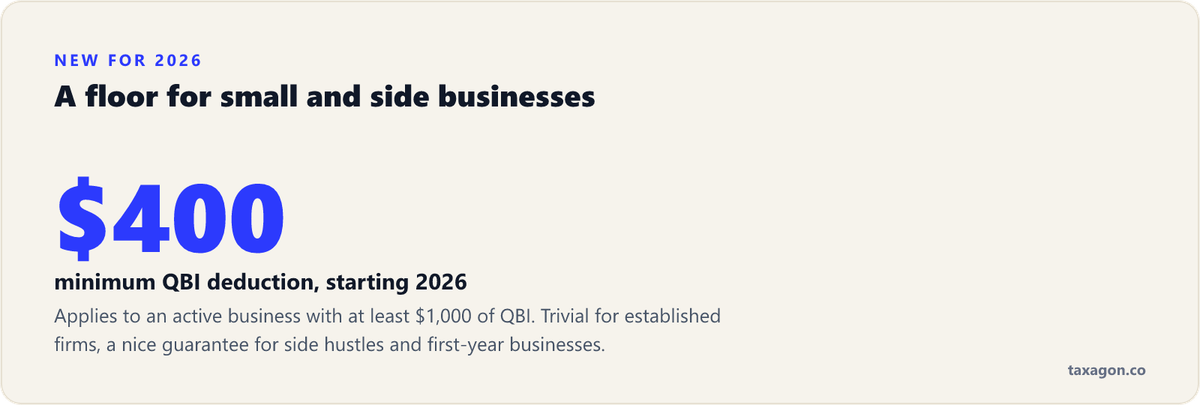
Starting in 2026, an active business with at least $1,000 of QBI gets a minimum $400 deduction — trivial for established firms, a nice guarantee for side hustles and first-year businesses.

Permanence changes the posture: this is no longer a use-it-before-it-dies provision but a 20% structural discount to design your compensation and retirement strategy around. If nobody has modeled your QBI position since the law changed, that's a gap worth closing before December.
This guide is the hub — each of these covers one specific situation in detail:
Talk it through with a licensed US tax professional — we'll tell you honestly whether it applies to your situation.