For fifteen years, crypto taxation ran on the honor system. That system is gone. Exchanges began filing Form 1099-DA with the IRS for 2025 sales, and starting with assets bought in 2026, they report your cost basis too. The IRS's matching computers now see crypto the way they've always seen stocks — which makes this the year to get your records straight.
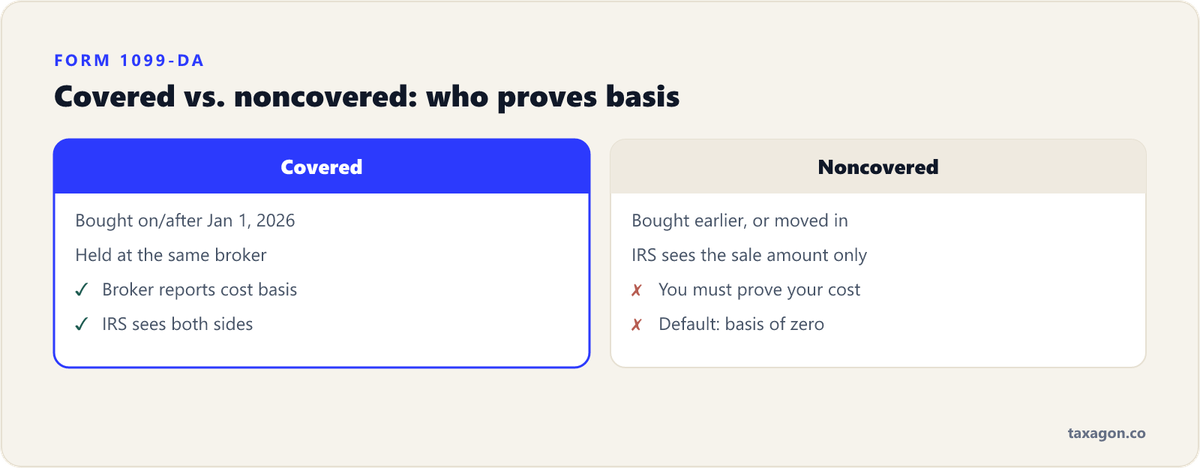
Custodial brokers — Coinbase, Kraken, hosted wallets, payment processors — now report your gross proceeds to the IRS. For assets acquired on or after January 1, 2026 and held at the same broker, they'll also report cost basis ('covered' assets). Anything bought earlier, or transferred in from elsewhere, is 'noncovered' — the IRS sees the sale amount but not your cost. If you don't prove basis, the default assumption is the worst one: basis of zero, tax on the whole proceeds.
The old 'universal' method — pooling all your BTC everywhere as one lot — is dead. Basis now tracks per wallet, per account. Coins moved between wallets carry their basis with them, which means your transfer history matters as much as your trade history. Every serious holder now needs crypto tax software (or an accountant driving it) reconciling every wallet — DeFi and cold storage included, since those don't get 1099s at all.
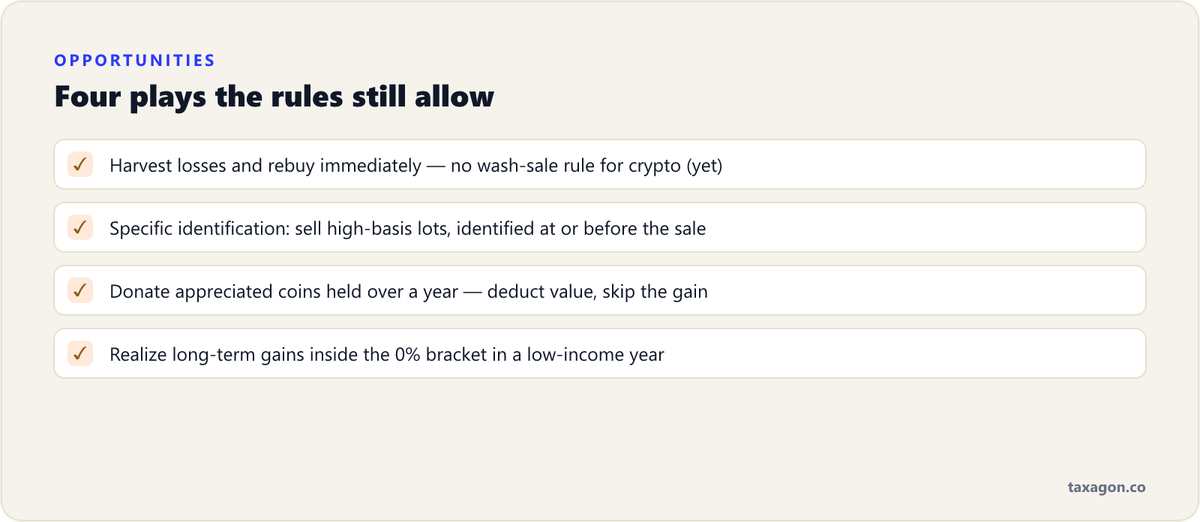
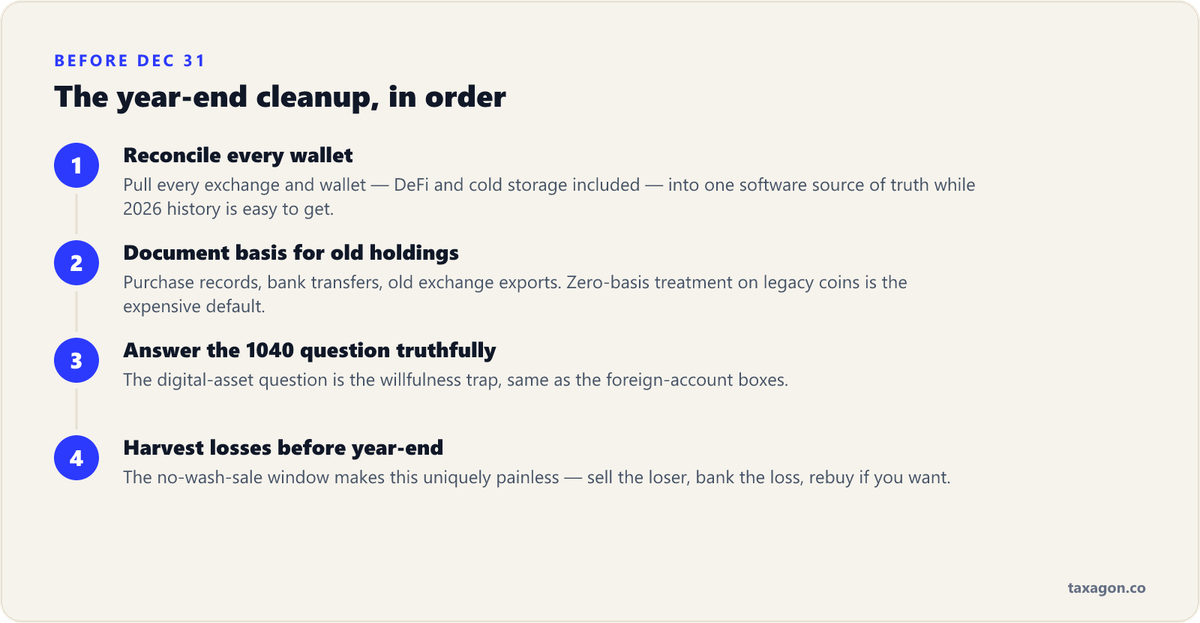
If your crypto records are a shoebox of screenshots across five exchanges and three wallets, you're the person the new matching regime was built to find. Cleaning it up in October is a project; explaining it to the IRS in an audit is a nightmare. We do the former.
This guide is the hub — each of these covers one specific situation in detail:
Talk it through with a licensed US tax professional — we'll tell you honestly whether it applies to your situation.