The US tax system is pay-as-you-go. Employees never notice because withholding does it for them. The moment you have income without withholding — self-employment, S corp distributions, RSU sales, rental profit, big interest income — the IRS expects four payments a year, and charges interest-like penalties when it doesn't get them.
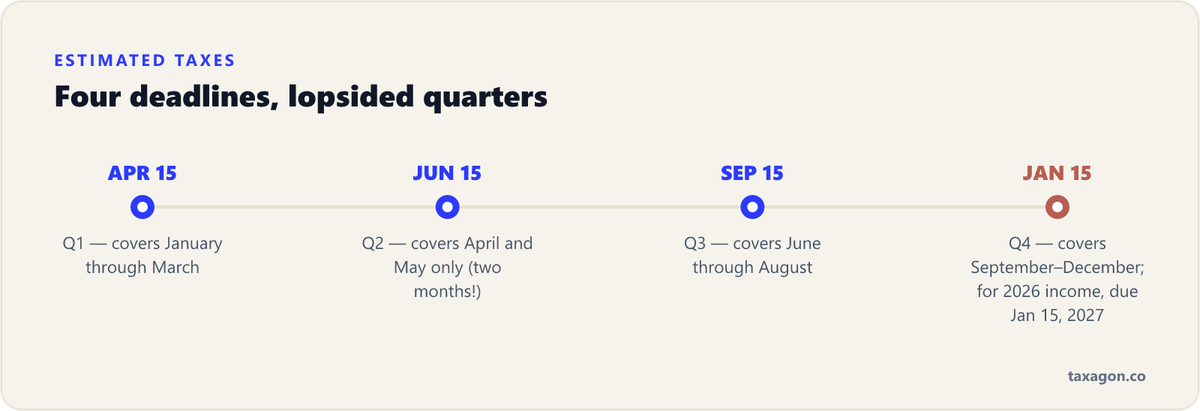
The lopsided quarters matter: June sneaks up two months after April, and Q4 for 2026 income is due January 15, 2027 — after the holidays, before most people think about taxes.

You owe no underpayment penalty for 2026 — no matter how much you end up owing in April — if your timely payments (withholding + estimates) hit any one of these:
Rule of thumb: income going up? Pay 110% of last year and invest the difference until April. Income going down? Project the current year and pay 90% of that instead.
Estimates are credited when paid — but withholding is treated as spread evenly across the year no matter when it happens. Under-paid all year? A large December bonus withholding, an extra S corp salary run with heavy withholding, or a December retirement-plan distribution with withholding can erase penalties that estimates no longer can. This is the single best November/December rescue tool.
Lumpy income — a big Q4 client payment, a September stock sale — doesn't require equal quarterly payments. Form 2210's annualized method matches payments to when income actually arrived. More paperwork, real savings for seasonal businesses.
Your salary carries withholding, but pass-through profit needs estimates on your personal return. New S corp owners get blindsided by this every year — the first-year fix is setting estimates the same month the election is filed.

The working system is boring: a separate tax savings account, an automatic transfer of 25–30% of every owner draw, IRS Direct Pay on four calendar reminders, and one November check-in to true-up. That last step — the Q4 true-up — is where a professional pays for themselves, because it's the last chance to use the withholding trick while it still counts.
This guide is the hub — each of these covers one specific situation in detail:
Talk it through with a licensed US tax professional — we'll tell you honestly whether it applies to your situation.