When federal BOI reporting died for U.S. companies, the immediate question from New York business owners was: “Doesn’t New York have its own version?” It does — the New York LLC Transparency Act, which took effect January 1, 2026. And in a plot twist that mirrored the federal story almost beat for beat, its scope collapsed just before launch. Here’s where it actually stands.
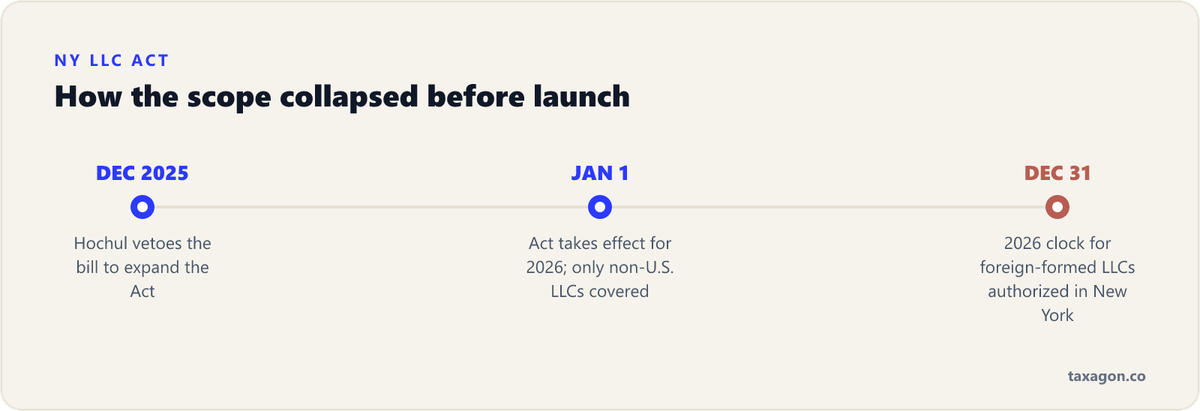
If your LLC was formed anywhere in the United States, you have nothing to file with New York. In December 2025, Governor Hochul vetoed the bill that would have expanded the Act, and the New York Department of State confirmed that the law applies only to LLCs formed outside the United States that are authorized to do business in New York.
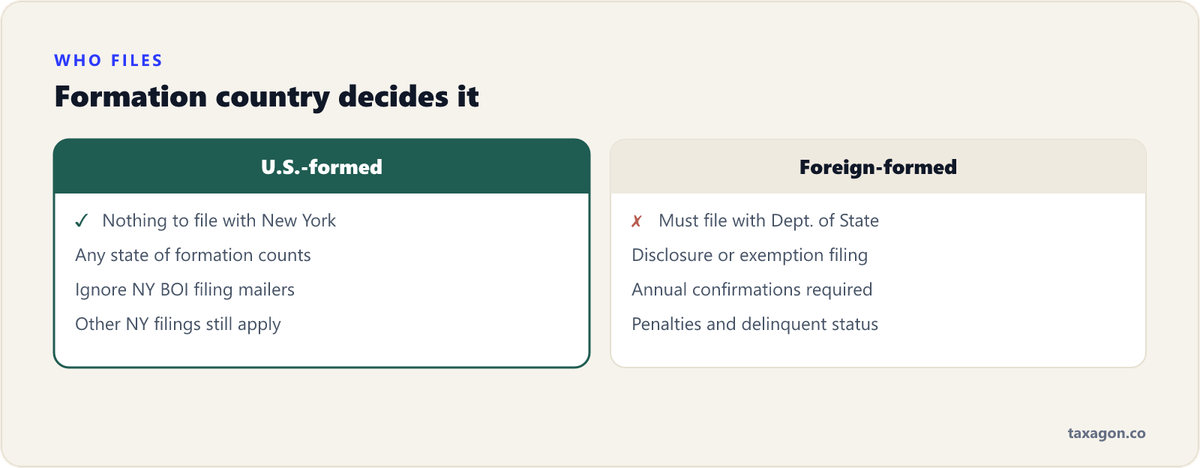
Foreign-country LLCs (not merely out-of-state ones) registered to do business in New York must file with the Department of State either a beneficial ownership disclosure or an attestation of exemption if they qualify for one of the Act’s exemption categories, which track the federal CTA’s list (banks, insurers, large operating companies, and so on). The deadlines:
Ongoing, covered LLCs must keep their information current with annual confirmations, and non-compliance can lead to being flagged delinquent with the state and monetary penalties.
Both the federal CTA and New York’s Act ran into the same wall: courts and policymakers balked at forcing tens of millions of small domestic companies into ownership databases to catch a small number of bad actors, most of whom operate through foreign entities anyway. Both regimes landed in the same place — watch the foreign entities, leave domestic small business alone. Other states have floated their own transparency bills (California has tried more than once), so the concept isn’t dead nationally. If a state where you operate passes one, the pattern to expect is the one you’ve now seen twice.
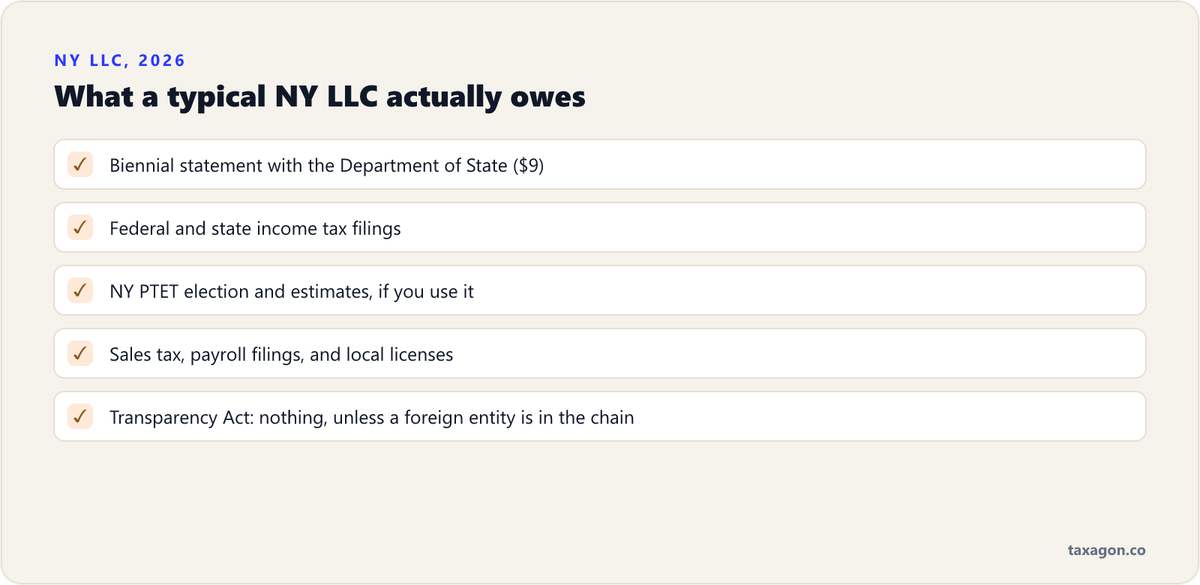
If there’s any foreign entity anywhere in your ownership chain, that’s worth a fifteen-minute review well before December — state deadlines are cheaper to meet than to fix.
Talk it through with a licensed US tax professional — we'll tell you honestly whether it applies to your situation.