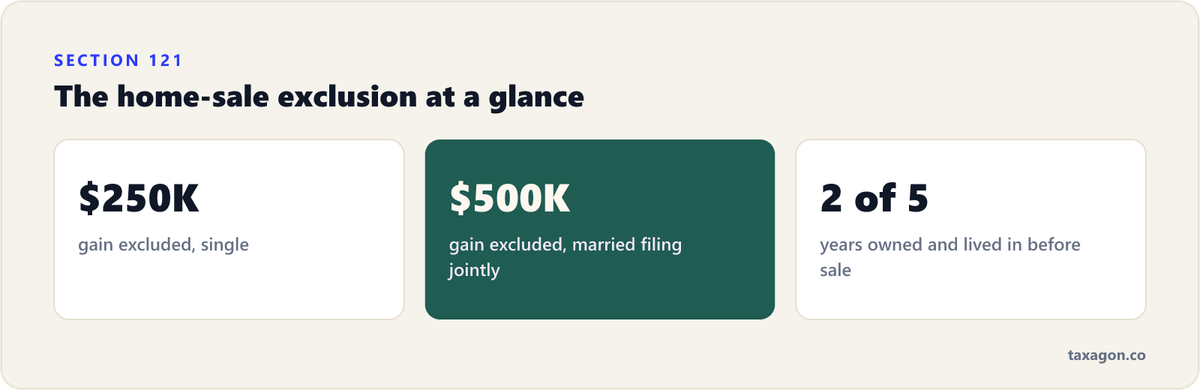
Sell your main home and up to $250,000 of gain — $500,000 if married filing jointly — is simply tax-free, under Section 121 of the tax code. The test is short: you must have owned the home and used it as your principal residence for at least 2 of the 5 years ending on the sale date. Pass it, and for most families the entire profit disappears from the tax return. No age requirement, no rollover into a new house, no once-in-a-lifetime limit — you can use it repeatedly, generally once every two years.
A home sale is usually the largest single gain most people ever realize, and it often travels with other big changes — a new city, a marriage, a growing family — which is why it anchors a section of our life-events tax guide. Below: how the 2-of-5 test works, how to compute the gain correctly (basis is where people overpay), the partial exclusion when life forces an early sale, and the rental-conversion traps.
Both requirements — ownership and use — must be met for 24 months (730 days) within the 5 years before closing, but the months don't have to be continuous and the two tests don't have to overlap. Live in a home for two years, rent it out for up to three, then sell: still qualified. A few clarifications that answer most real-world questions:
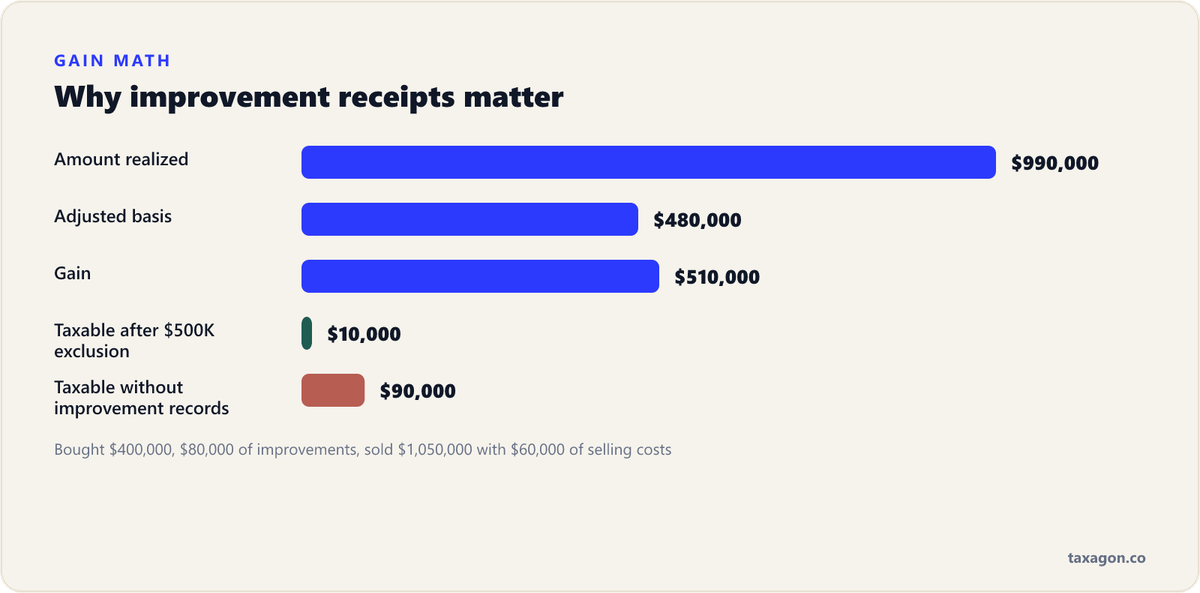
Your taxable gain is the amount realized minus your adjusted basis, and both ends are adjustable in your favor:
Worked example. A couple bought for $400,000, spent $80,000 on improvements over fifteen years, and sells for $1,050,000 with $60,000 of selling costs. Amount realized: $990,000. Adjusted basis: $480,000. Gain: $510,000 — of which $500,000 is excluded, leaving just $10,000 of taxable long-term gain. Without the improvement records, the gain would be $590,000 and the taxable slice $90,000. That's why the single best habit of homeownership is a folder (digital is fine) of every improvement receipt, kept for as long as you own the home plus three years.
Whatever gain survives the exclusion is a long-term capital gain, taxed at capital-gains rates — and depending on your other income that year, some of it may even land in the 0% bracket, a possibility worth timing for, as we explain in our guide to the 0% capital gains bracket. Large surviving gains can also attract the 3.8% net investment income tax above $200,000 single / $250,000 MFJ MAGI.
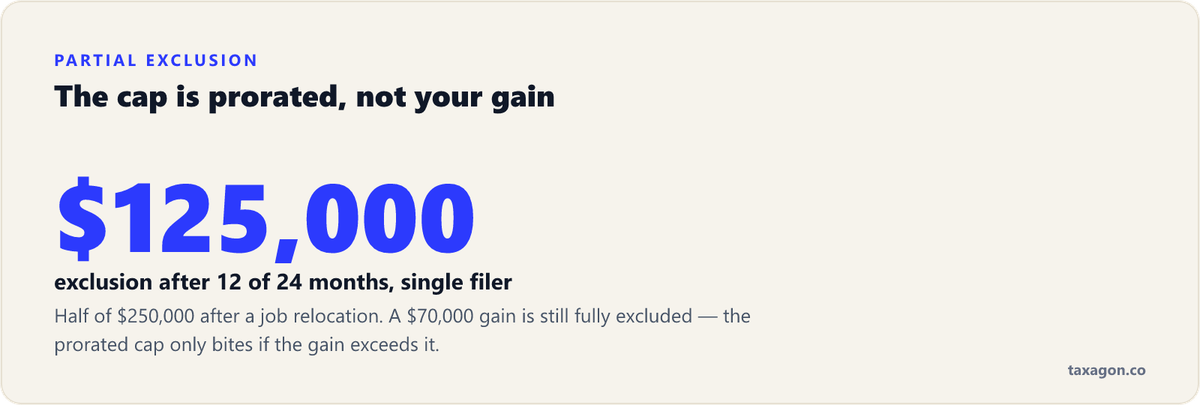
Fail the two-year test and you don't automatically lose everything. If the primary reason for the early sale is a change in place of employment, health, or certain unforeseen circumstances (divorce, multiple births, a death in the family, and similar events), you get a pro-rated exclusion — and note carefully: it's the exclusion cap that gets prorated, not your gain.
Example: a single owner lives in a home 12 months, then a job relocation forces a sale. Twelve months is half of the required 24, so the cap becomes half of $250,000 = $125,000. If the gain is $70,000, the entire gain is still excluded — the prorated cap only bites if your gain exceeds it. For most short-tenure sales with a qualifying reason, the partial exclusion wipes out the whole gain. The job-change trigger has a working rule of thumb: a new job location substantially farther from the home than the old one generally qualifies. If you're selling early because of a move, the state-tax side of that move has its own rules — see our guide to moving states mid-year.
The exclusion gets complicated when the home hasn't been purely your residence:
If any of these apply, this is a return worth professional preparation — the interaction of recapture, nonqualified use, and the exclusion is where DIY filings go wrong.
If your entire gain is excluded and you receive no Form 1099-S from the closing agent, the sale generally doesn't need to appear on your return at all. If a 1099-S was issued (title companies often issue them routinely), report the sale on Form 8949 and Schedule D and claim the exclusion there — otherwise the IRS computer sees gross proceeds with no return entry and sends a mismatch notice. And any gain above the exclusion is reportable regardless. Losses on a personal residence, for the record, are never deductible.
Own and live in your home for 2 of the last 5 years and Section 121 excludes up to $250,000/$500,000 of gain; keep improvement receipts to shrink whatever's left; claim the pro-rated exclusion if a job, health, or unforeseen event forces an early sale; and watch for depreciation recapture the moment a rental history enters the picture. Taxagon's CPAs and EAs handle home-sale reporting and exclusion planning for individual clients every season — if your sale has a wrinkle, reach out before you close.
This article is general information, not tax advice for your specific situation. Tax law changes; figures are for the years stated.
Talk it through with a licensed US tax professional — we'll tell you honestly whether it applies to your situation.