The right retirement plan for your business depends on exactly two questions: do you have employees, and how much do you want to put away? No employees: a solo 401(k) or SEP IRA, each allowing up to $72,000 for 2026. Employees: a SIMPLE IRA for low cost and low admin, or a safe-harbor 401(k) for bigger limits — with SECURE 2.0 startup credits now covering most of the setup cost either way. And for high-income owners 50 and up who want to put away far more, a cash balance plan stacks a six-figure deduction on top.
Every one of these is a current-year deduction machine as much as a retirement vehicle, which is why plan selection sits in the fourth quarter of our year-round tax playbook — several of these plans must exist before year-end to count for the year. Here's the ladder, from simplest to most powerful.
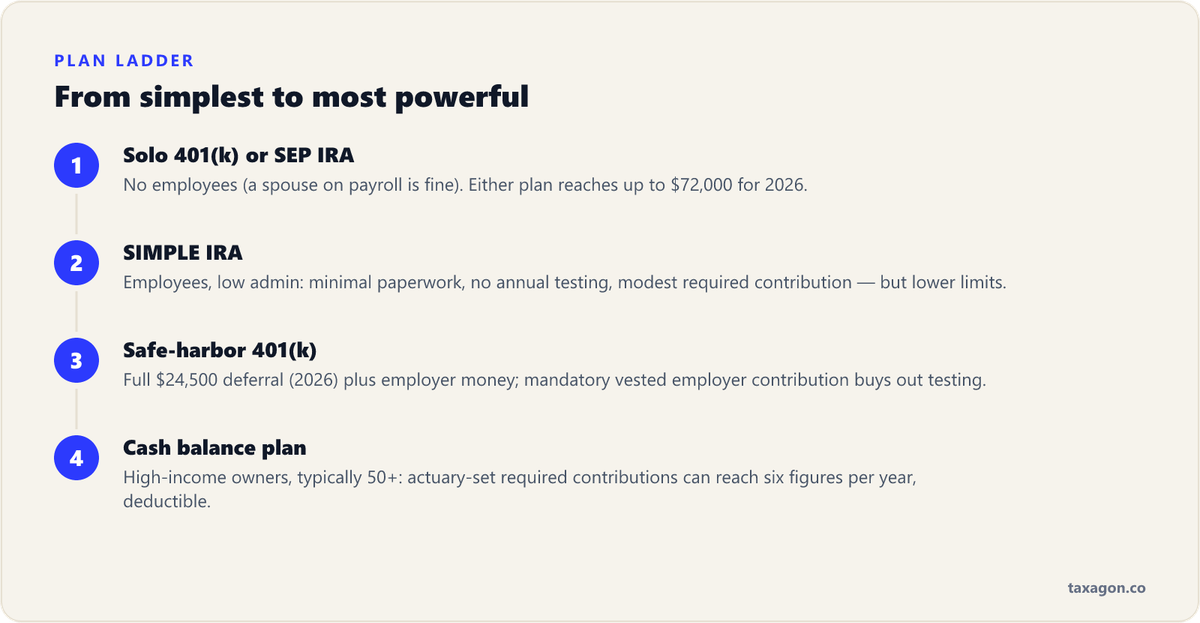
If it's just you (a spouse on payroll doesn't break eligibility), you have two main options, and both cap at the same $72,000 total for 2026 — but they get there differently.
Concrete example: at $80,000 of self-employment profit, a SEP's percentage-of-comp formula allows a fraction of what a solo 401(k) reaches once the $24,500 deferral is stacked on the employer piece. The full head-to-head — contribution math, Roth angles, when each wins — is in our solo 401(k) vs. SEP IRA face-off for freelancers.

Once you have eligible employees, the game changes: most plans require you to contribute for them, and nondiscrimination rules stop you from loading up your own account while giving staff nothing. The two workhorse choices:
The honest framing: a SIMPLE costs less to run and less in required contributions; a safe-harbor 401(k) costs more and lets you save two to three times as much personally. Decide based on your own target contribution first, then check the employer-contribution cost against your headcount.
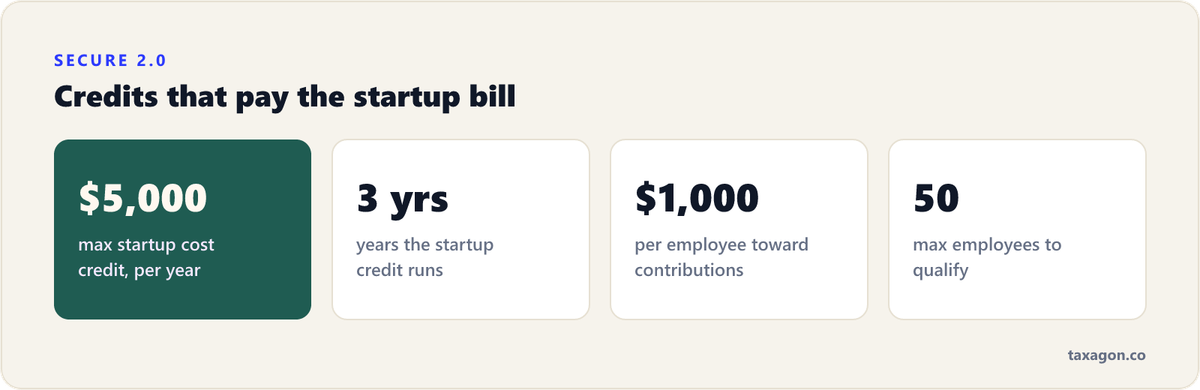
The classic objection — "a plan costs too much to set up" — mostly died with SECURE 2.0. For employers with up to 50 employees, two credits stack:
Between the two, a small team's plan can run effectively free for its first few years — the credits offset both the provider fees and a meaningful chunk of the required contributions. If employee costs were what kept you on the sidelines, rerun the math with the credits in it. And remember the contributions themselves are deductible compensation costs on top of the credits.
For owners with consistently high income — typically 50 and older, because the mechanics favor shorter horizons — a cash balance plan is the heavy artillery. It's a defined-benefit plan: instead of capping what goes in each year, the law caps the benefit you're funding toward, and an actuary calculates the annual contribution needed to get there. For an older owner with a short runway to that benefit, the required contribution can reach six figures per year — deductible — stacked on top of a 401(k).
The commitments that come with it:
For the right profile — a 55-year-old consultant or practice owner clearing high six figures who wants to compress twenty years of saving into ten — nothing else in the tax code moves this much money pre-tax. Pair it with other late-career moves like putting family on payroll where genuine work exists; our guide to hiring your kids in the business covers that adjacent play.
Choose the plan by your target contribution and headcount; choose the timing by the deadline that's still open.
Plan establishment sits alongside the other expiring moves on our December year-end checklist, and the contribution decision belongs in a projection meeting, not a guess — this is exactly the modeling a tax planning engagement is built around.
The ladder is simple: solo 401(k) or SEP up to $72,000 (2026) when you're solo; SIMPLE or safe-harbor 401(k) once you have a team, with SECURE 2.0 credits paying most of the startup bill; cash balance on top when income is high and the horizon is short. The expensive mistake isn't picking the second-best plan — it's picking none and donating the deduction. Taxagon's CPAs and EAs model plan choices against real profit numbers for owners every fall — if you want the math run on yours, reach out.
This article is general information, not tax advice for your specific situation. Tax law changes; figures are for the years stated.
Talk it through with a licensed US tax professional — we'll tell you honestly whether it applies to your situation.