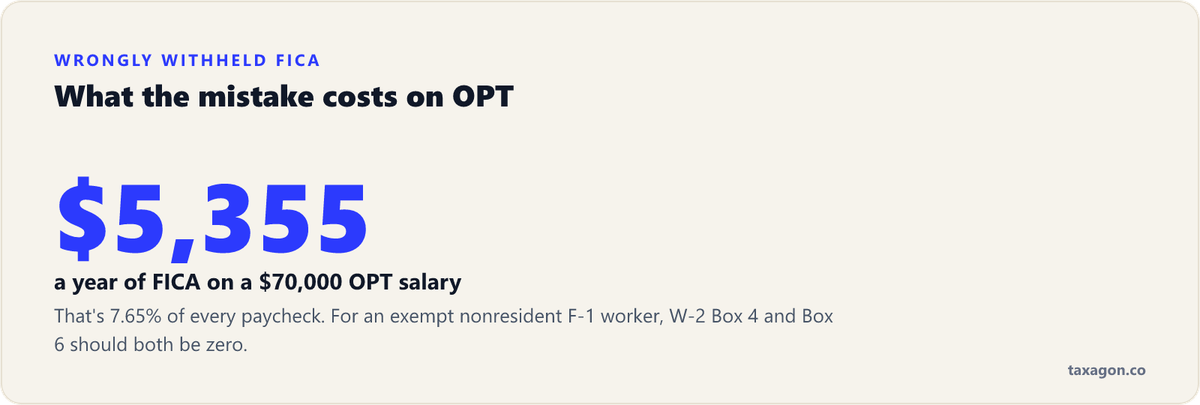
Here's the short answer: if you're on F-1 status — including OPT and STEM OPT — and you're still a nonresident alien for tax purposes, you should not be paying Social Security and Medicare (FICA) taxes on your wages. That's 7.65% of every paycheck. Employers get this wrong constantly, especially when an OPT hire goes through the same onboarding system as everyone else, and the money is recoverable.
This post covers why the exemption exists, how to check whether it applies to you, how to get wrongly withheld FICA back, and what changes when your five-year clock runs out or you switch to H-1B. It's one piece of the bigger cross-border picture we lay out in The NRI's Complete Guide to US Taxes.
The exemption has two layers. First, F-1 students are exempt individuals for the substantial presence test during their first five calendar years in the US. Exempt doesn't mean exempt from tax — it means your days physically in the US don't count toward the residency test. Since you're not counting days, you stay a nonresident alien for tax purposes. The mechanics of that day-counting rule are worth understanding — see our substantial presence test guide with worked examples.
Second, wages paid to nonresident F-1 students for work connected to their status — on-campus jobs, CPT, OPT, STEM OPT — are exempt from FICA. Put together: as long as the five-year exemption keeps you a nonresident, your paycheck should show federal and state income tax withholding, but no Social Security and no Medicare.
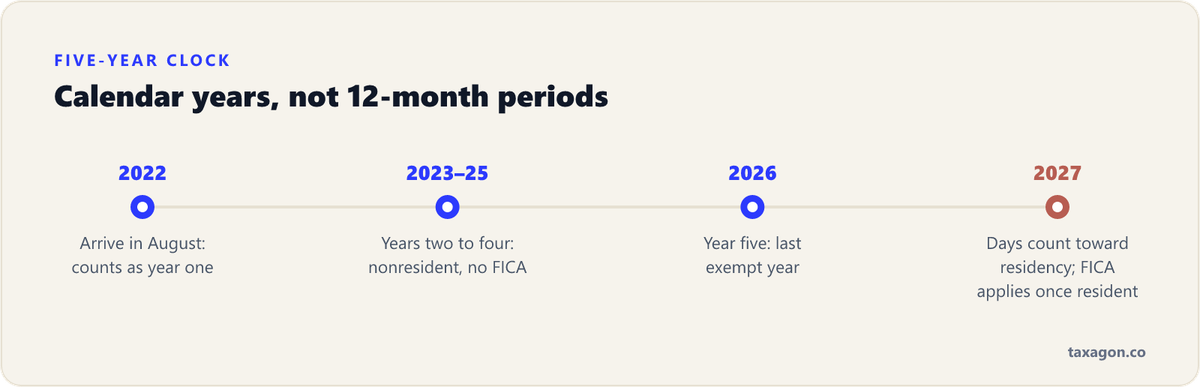
Note that the five years are calendar years, not 12-month periods. Arrive in August 2022 and 2022 counts as year one, even though you were only here five months. Your exempt years would be 2022 through 2026.
Pull up a pay stub or your W-2 and look for these:
If there are amounts in those boxes and you were a nonresident on F-1 all year, your employer withheld tax you never owed. On a $70,000 OPT salary, that's about $5,355 a year sitting with the IRS.
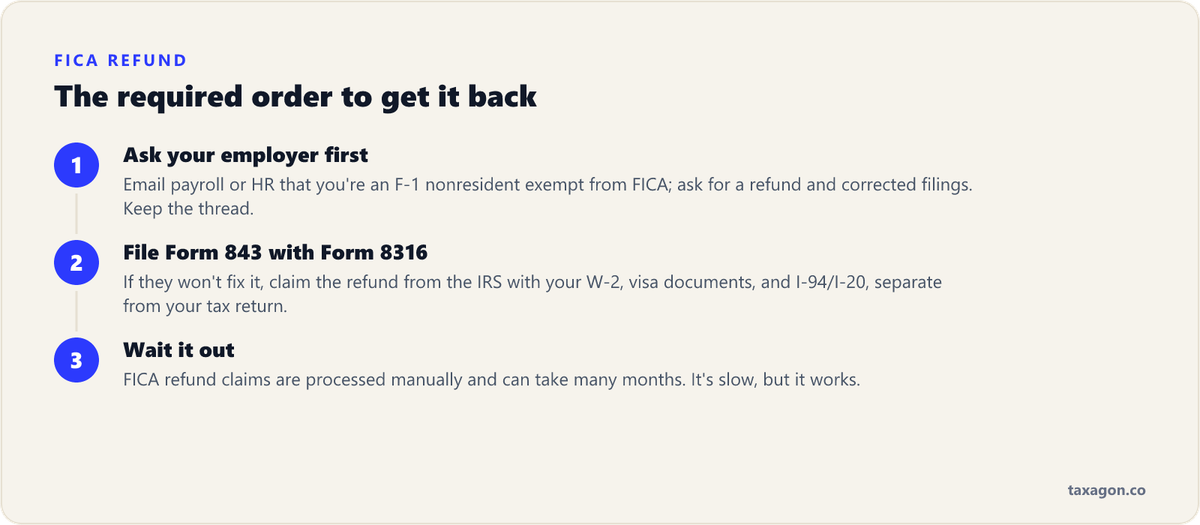
The refund path has a required order:
FICA is only half the story — you still file an income tax return. As a nonresident, that's Form 1040-NR, which taxes only your US-source income. Nonresidents normally get no standard deduction, but Indian students are the big exception: Article 21(2) of the US-India tax treaty lets students from India claim the standard deduction on a 1040-NR — $16,100 for a single filer in 2026. That treaty benefit alone saves Indian students real money every year, and it disappears if you file the wrong form.
Two cautions. Don't use standard consumer tax software defaults — most mainstream products prepare resident 1040s and will happily misfile you as a resident. And don't claim the treaty deduction after you've become a resident filing a 1040; the Article 21(2) benefit is for students filing as nonresidents.
The FICA exemption is not permanent. It ends when either of two things happens:
A common trap in the transition: an employer who correctly stopped FICA during OPT sometimes forgets to start it when the H-1B kicks in. That error runs in your favor short-term but creates a real liability — flag it.
Nonresident F-1 students and OPT workers don't owe FICA, and Indian students get the standard deduction on their 1040-NR under the treaty. If FICA was withheld anyway, request a refund from your employer, and file Form 843 with Form 8316 if they don't deliver. Taxagon's CPAs and EAs handle 1040-NRs, treaty positions, and FICA refund claims for students every season — if you'd rather have it done right the first time, our NRI and international student services are here.
This article is general information, not tax advice for your specific situation. Tax law changes; figures are for the years stated.
Talk it through with a licensed US tax professional — we'll tell you honestly whether it applies to your situation.