If you live in the US and have any financial life left in India — NRE/NRO accounts, mutual funds, property, rent from a flat in Bangalore — you're operating in two tax systems at once. The income tax part is manageable. The disclosure part is where lives get ruined, because the penalties aren't for unpaid tax — they're for unfiled paper.
Step one: which system owns you?
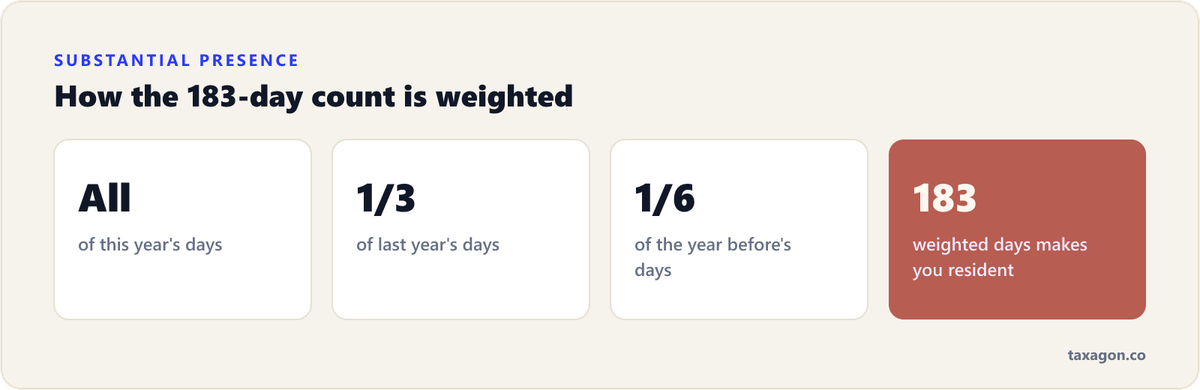
The US taxes its tax residents on worldwide income. You're a tax resident if you hold a green card, or pass the substantial presence test — roughly 183 weighted days across three years (this year's days + 1/3 of last year's + 1/6 of the year before). H-1B, L-1, and most work-visa holders become residents quickly. F-1 students are exempt from the count for five calendar years, which is why students often file as nonresidents while their H-1B colleagues can't.
Once resident: your Indian salary history doesn't matter, but every rupee of current Indian income — NRO interest, mutual fund gains, rent, dividends — belongs on your US return, converted to dollars.
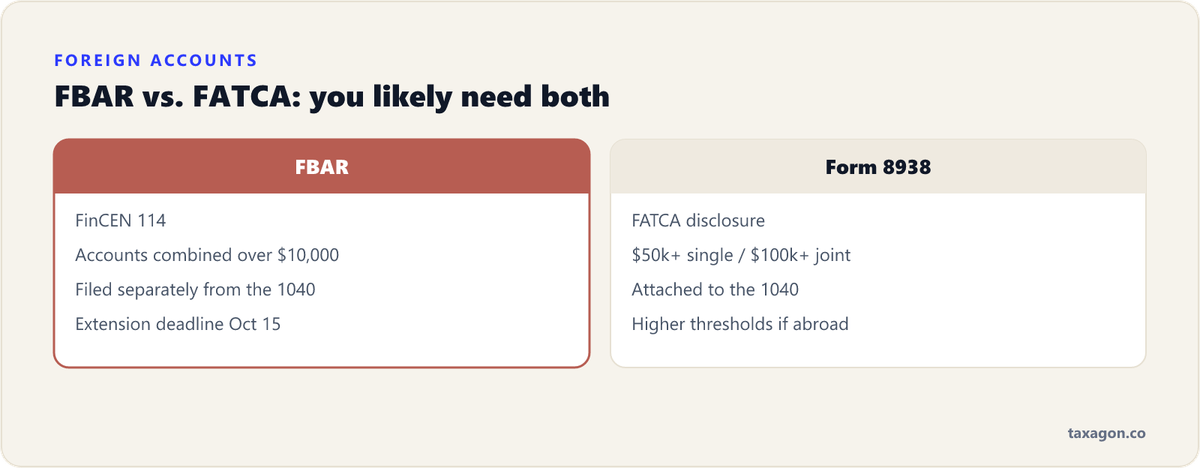
- FBAR (FinCEN 114): required if your foreign accounts combined exceeded $10,000 at any moment in the year. Every account gets listed — NRE, NRO, FDs, even accounts you merely hold signing power over. Non-willful violations start around $10,000+ per year; willful ones can reach half the account balance. Filed separately from the tax return; the extension deadline is October 15.
- Form 8938 (FATCA): similar disclosure attached to the 1040 at higher thresholds ($50k+ single / $100k+ joint, higher for those living abroad). Yes, it overlaps FBAR; yes, both are required.
- Form 8621 (PFIC): the nasty one. Indian mutual funds and ULIPs are 'passive foreign investment companies' to the IRS — taxed under punitive default rules with interest charges that can eat the entire gain, plus a form so complex the IRS estimates dozens of hours per fund. Practical takeaway: US residents should think hard before holding Indian mutual funds at all; US-domiciled funds achieve the same exposure without the poison.
- Schedule B, Part III: those two little foreign-account checkboxes are how the IRS establishes you knew — answering them wrong converts 'oops' into 'willful.'
The treaty: what it actually does for you
- No double tax, by credit: India taxes your NRO interest via TDS at ~30%; the US taxes it too, but Form 1116 gives you a foreign tax credit for Indian tax paid. You net out at the higher of the two rates, not the sum.
- Indian salary earned before you moved isn't US-taxed if you weren't yet a resident; dual-status first years deserve professional handling.
- Selling Indian property: India applies TDS on the sale and taxes the gain; the US taxes the gain too (with basis, often stepped by the old exchange rate math) and credits the Indian tax. The paperwork spans both countries and two filing seasons — plan the sale, don't just do it.
- Indian retirement (EPF/PPF): gray areas exist; interest is often US-taxable annually even while locked in India. This is a name-your-facts situation.
Coming clean if you're behind
Thousands of NRIs discover FBAR years late. The IRS's Streamlined Filing Compliance Procedures exist exactly for this: refile 3 years of returns, 6 years of FBARs, certify the failure was non-willful, and penalties drop to zero (for those abroad) or 5% (domestic) — versus the catastrophic default. Quiet disclosure (just starting to file 'from now on') is the tempting wrong answer that forfeits the program's protection.
The annual NRI checklist
- Count your days; know your residency status before you file anything.
- List every Indian account with its peak balance — FBAR by October 15.
- Report NRO/NRE interest, MF gains, rent — with Form 1116 credits for Indian TDS.
- Flag any Indian mutual funds for PFIC handling — or better, restructure out of them.
- Selling property or repatriating large sums this year? Get advice before the transaction.
This is our home turf — cross-border India-US filings are a Taxagon specialty. If any item above made your stomach drop, a 30-minute call will tell you exactly where you stand.
Go deeper in this series
This guide is the hub — each of these covers one specific situation in detail: